MYTH
"You can only use it once."
The truthIt's a lifetime benefit. Sell the home and pay off the loan, and you get it back to use again. Many people even keep their first home as a rental and buy the next one with VA.
VA home loans · Lending in all 50 states
A VA loan is a home loan backed by the Department of Veterans Affairs. It lets Veterans, service members and surviving spouses buy a home with no money down and no monthly mortgage insurance. We'll walk you through it in plain English, in any state.
What people get wrong
These keep a lot of military families from using a benefit they earned. Here's the truth, in plain terms.
"You can only use it once."
The truthIt's a lifetime benefit. Sell the home and pay off the loan, and you get it back to use again. Many people even keep their first home as a rental and buy the next one with VA.
"You need perfect credit."
The truthThe VA doesn't set a minimum score. Many lenders work with scores in the 580 to 620 range, and a rough patch in your past doesn't automatically rule you out.
"Sellers won't take a VA offer."
The truthA VA offer with a solid pre-approval competes with anyone. The VA appraisal just makes sure the home is safe and fairly priced, so you don't overpay.
"Everyone pays the VA fee."
The truthIf you get VA disability pay, you pay no fee at all. Everyone else can add the one-time fee to the loan instead of paying it in cash.
"It's only for retirees or combat vets."
The truthActive-duty members usually qualify after 90 days. Guard and Reserve members, peacetime Veterans and many surviving spouses qualify too.
"VA loans cost more."
The truthUsually the opposite. There's no monthly mortgage insurance, and VA rates are often lower than conventional rates. That can mean a smaller monthly payment.
Side by side
For most eligible buyers, a VA loan costs less each month, mainly because it needs no down payment with full entitlement and has no monthly mortgage insurance.
| Feature | VA loan | FHA loan | Conventional loan |
|---|---|---|---|
| Minimum down payment | $0 with full entitlement | 3.5% with a 580+ credit score | Usually 3% to 5% |
| Monthly mortgage insurance | None | Yes, a yearly premium, often for the life of the loan with less than 10% down | Yes with less than 20% down, until you reach about 20% equity |
| Upfront fee | VA funding fee of 0.5% to 3.3%; $0 with VA disability pay | 1.75% upfront mortgage insurance | None |
| Minimum credit score | No VA minimum; lenders often look for 580 to 620 | 580 for 3.5% down, 500 with 10% down | Usually about 620 |
| Loan limit | None with full entitlement | County FHA limits | Conforming limits, set every year |
| Seller concessions | Up to 4%, plus normal closing costs | Up to 6% | 3% to 9%, depending on down payment |
| Assumable by a future buyer | Yes, with approval | Yes, with approval | Usually no |
| Who can use it | Eligible Veterans, service members and some surviving spouses | Anyone who qualifies | Anyone who qualifies |
VA figures: VA.gov funding fee and closing costs and the VA Lender's Handbook. FHA and conventional figures are general program guidelines as of October 2026. Your lender confirms what applies to you.
Moving on orders?
We lend in every state, so you don't have to find and vet a new lender each time the military moves you. Same team, same process, from your first home to your last.
Where are you headed?
Ballpark your payment
Plug in a home price to see a rough monthly payment with a VA loan.
The "VA fee" is a one-time charge that keeps the program running. Most people add it to the loan, so it doesn't come out of pocket. If you get VA disability pay, it's $0.
*30-year fixed, principal and interest only. Property taxes, insurance and HOA dues will add to this. This is an estimate, not a rate quote or loan offer.
More than buying
A house, condo or townhome. Even a duplex up to a fourplex if you live in one unit.
Already have a VA loan? Refinance to a lower rate with less paperwork.
Called a "VA streamline" or IRRRLUse your home's value to pay off credit cards, fix up the house or cover big expenses.
Some sellers have VA loans from years ago at lower rates. You may be able to take theirs over.
Called a "loan assumption"How it works
A quick call about where you're headed, your timeline and your budget.
We confirm you qualify online, then show you what you can comfortably afford.
Shop with a pre-approval letter so sellers take your offer seriously.
Sign your final paperwork and move in. Your person on our team keeps you updated the whole way.
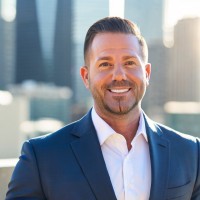
Your loan team
For over two decades, Jason has served the military community that served all of our families. Today he leads a small VA loan team at Texana Bank that helps Veterans, service members and surviving spouses buy and refinance homes in all 50 states.
The team is small on purpose. Every client gets one person who knows their file, explains every number in plain English, and tells them straight when waiting is the better move. Many of those clients are on PCS orders with tight timelines, and the team knows how to work around them.
"Serving the military community that served all of our families."Jason Stevens, NMLS #195798
How we work
Verify Jason's NMLS registration · More about Jason and the team →
Straight answers
For most eligible buyers, yes. A VA loan needs no down payment with full entitlement and has no monthly mortgage insurance. FHA requires at least 3.5% down and charges a yearly mortgage insurance premium. See the side-by-side table above.
With no down payment, you mainly need money for closing costs, which often run 2% to 5% of the price. Sellers can pay many of those costs, so some buyers bring very little.
Yes. You can buy a home with up to four units as long as you live in one of them. Rent from the other units may help you qualify.
Most VA purchases close in about 30 to 45 days, about the same as other loan types.
If you've never used your benefit, or you've fully restored it, the VA sets no loan limit. You still need the income to afford the payment.
Often, yes. If your spouse died in service or from a service-connected condition and you haven't remarried, or remarried after age 57, you may qualify.
Just a conversation. We can usually confirm your eligibility online. Later you'll send pay stubs or your LES, bank statements and, for Veterans, your DD-214.
Get started
Tell us a little about your plans. Jason or someone on his team will follow up within one business day, and that person stays with you the whole way. No cost, no pressure.
Call or text(888) 494-VETS (888-494-8387)
Email[email protected]
ServingAll 50 states
Ready to apply?Start your secure application